
Ray Dalio
Founder of Bridgewater Associates, the world's largest hedge fund — a macro investor known for "Principles," the All-Weather portfolio, and a systematic, diversified approach to risk.
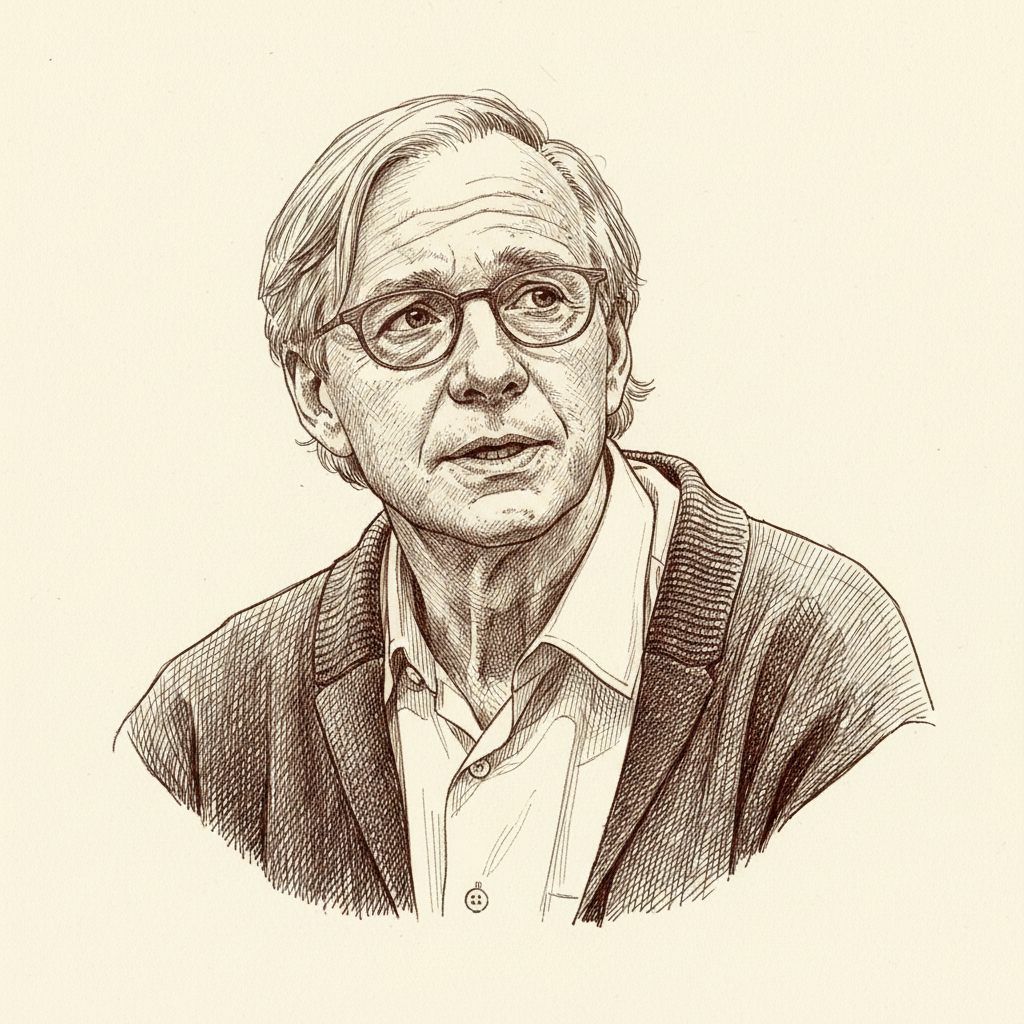
Who he is

Ray Dalio founded Bridgewater Associates in 1975 out of his apartment and grew it into the world's largest hedge fund, managing money for governments, pensions, and institutions.
He is widely known for his best-selling book "Principles," for the All-Weather portfolio concept, and for promoting a culture of "radical transparency" and idea-meritocracy at Bridgewater.
Core philosophy
Dalio thinks in terms of the economic machine — debt cycles, productivity, and how policy drives markets. He favors true diversification across uncorrelated return streams rather than concentrating in one bet.
The All-Weather idea is to balance risk across assets so the portfolio performs reasonably in any economic environment — growth or recession, inflation or deflation — rather than predicting which will come.
Key lessons for individual investors
- Diversify across truly uncorrelated assets, not just many similar ones.
- Balance risk, not just dollars, across your portfolio.
- Understand the economic machine — debt cycles drive long-term moves.
- Write down your principles and decision rules so you can learn from mistakes.
- You don't have to predict the future to build a resilient portfolio.
Live track record & latest portfolio
Real figures from public 13F filings and historical returns, via Bridgewater Associates. For education only — not investment advice, and not a recommendation to copy any position.
Source: GuruFocus. Figures are delayed and may be revised.
Ask Ray Dalio a question
Type a question about Ray Dalio's classic investment theories, or pick one below.
Half a billion dollars a week, into the panic
Sensing late-cycle excess in 2007, Howard Marks and Bruce Karsh raised a record ~$10.9 billion distressed-debt reserve fund at Oaktree — and then made investors wait while they deployed almost none of it. The memos kept repeating one idea: you cannot predict, but you can prepare.
In the fifteen weeks after Lehman fell, Oaktree invested roughly $500 million per week into the senior debt of fundamentally sound companies at desperate prices, while clients called asking if they had lost their minds. The fund became one of the most successful in distressed-investing history.
The riskiest moment is when everything feels safe; the safest is when everything feels hopeless. Position by the cycle, act when others cannot.
When the price already assumed a miracle
In 1972, institutions convinced themselves that about fifty "one-decision" growth stocks could be bought at any price and never sold. Polaroid traded above 90 times earnings, McDonald's and Disney near 80, Avon around 65. Run the arithmetic backwards and those prices quietly assumed decades of flawless, ever-accelerating growth.
The 1973–74 bear market repriced the dream: the group fell 60–90%, and Polaroid eventually went bankrupt. The cruel detail is that many of the businesses kept growing exactly as promised — the investments still failed, because the starting price had already spent the future.
Run the DCF backwards: ask what growth today's price assumes, then ask honestly whether reality can deliver it.
The courage to do nothing
At the top of the speculative "Go-Go" years, Buffett — after thirteen years compounding near 30% with no down year — wrote to his partners that he no longer understood the market and could find nothing sensible to buy. Rather than lower his standards, he closed the partnership and handed back the money at the peak of his fame.
Then he waited. When the 1973–74 crash finally arrived, he was liquid while everyone else was forced to sell, and described feeling "like an oversexed man in a harem" — buying the Washington Post and other franchises at panic prices that set up the next thirty years.
Cash and patience are positions too. Standards only count if you keep them when it is hardest.
Related tools
Frequently asked questions
What is the All-Weather portfolio?
Ray Dalio's concept of balancing risk across assets so a portfolio performs reasonably in any economic environment, rather than betting on one outcome.
What is Ray Dalio known for?
For founding Bridgewater Associates, writing "Principles," and popularizing risk parity and the All-Weather investing approach.
Pressure-test diversified, risk-balanced ideas:
Download Valuefocus