Margin of safety = (Intrinsic value − Price) ÷ Intrinsic valueTranscripts reveal what slides conceal: how management behaves when asked an unwanted question. Read the answers — and note the questions that never get one.
 Valuefocus
The observable warning signs — in the numbers, the disclosures, and management's language — that a thesis may be weaker than the story suggests.
Risk signals are concrete, checkable warning signs — in the financials, accounting, valuation, management behavior, or business — that an investment case deserves extra scrutiny. They are not predictions of disaster; they move a specific assumption from "trust it" to "verify it," and matter most when several cluster around the same weakness.
Risk signals are concrete, checkable indicators that something in an investment case deserves scrutiny. They are not predictions of disaster; they are flags that move an assumption from "trust it" to "verify it." A single signal rarely settles anything — a cluster of them changes the weight of evidence.
Good investors treat signals as questions, not verdicts: each one points to a specific thing to investigate before committing capital.
A company reports record net income, but free cash flow has fallen for three straight years while receivables grow faster than sales. Each fact is a risk signal. Together they raise a precise question: are reported profits turning into cash, or into IOUs? That is exactly the thing to verify before trusting the earnings.
"A risk signal means sell." A signal means investigate, not act. Many strong businesses carry one or two flags that, once understood, turn out to be benign or already priced in. The mistake is the opposite extreme too — ignoring a cluster of signals because you like the story. Signals exist to keep your conviction honest.
Margin of safety = (Intrinsic value − Price) ÷ Intrinsic valueTranscripts reveal what slides conceal: how management behaves when asked an unwanted question. Read the answers — and note the questions that never get one.
| Shortcut | The observable warning signs — in the numbers, the disclosures, and management's language — that a thesis may be weaker than the story suggests. |
|---|---|
| Disciplined workflow | They span financial, accounting, valuation, qualitative, and business categories. → A signal means investigate, not automatically sell. → They are fundamental and qualitative — different from technical chart sell signals. |
Practical guides on valuation, margin of safety, and reading businesses — straight to your inbox. No spam.
We respect your privacy. Unsubscribe anytime.
On Enron's April 17, 2001 earnings call, analyst Richard Grubman asked a basic question: why was Enron the only large financial firm that could not produce a balance sheet with its earnings? CEO Jeff Skilling's answer entered history — he called the analyst an "asshole" on the open line. The stock was near $60; Wall Street laughed along.
Readers of the transcript saw something else: a CEO with no answer to the simplest possible question. Those who kept following the calls heard the evasions multiply quarter after quarter. Skilling resigned in August "for personal reasons"; in December Enron filed the then-largest bankruptcy in US history. The warning had been published, word for word, ten months in advance.
Transcripts reveal what slides conceal: how management behaves when asked an unwanted question. Read the answers — and note the questions that never get one.
Berkshire Hathaway was a fading New England textile mill that Buffett bought into in the early 1960s because it was statistically cheap — and took control of in 1965 partly out of spite, after its CEO shaved an eighth of a dollar off a promised tender offer. For the next twenty years Buffett fed capital into newer looms while foreign competition ground prices ever lower.
No amount of good management could fix a commodity product with no moat. He finally closed the mills in 1985 and later called Berkshire "the dumbest stock I ever bought", estimating that the compounding forgone by not starting from an insurance company instead cost about $200 billion.
A low price cannot rescue a business with no moat. Knowing which problems are unfixable is what a circle of competence is for.
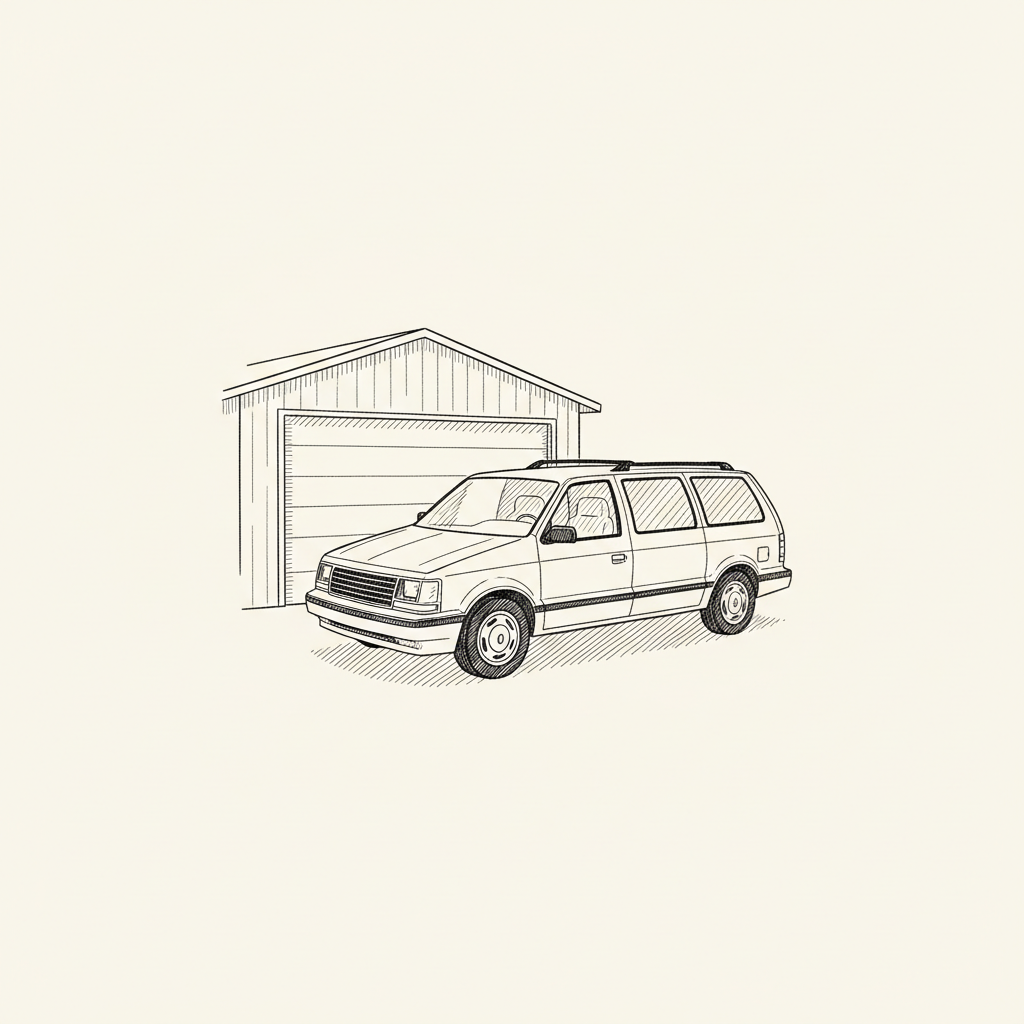
In 1982 the consensus said Chrysler was finished — the stock traded near $2 amid bankruptcy talk. Lynch did the unfashionable work: the balance sheet showed over $1 billion in cash after the government loan guarantee, giving it years of runway, and meetings with management revealed the upcoming minivan line.
He made Chrysler Magellan's largest position — not a small contrarian flutter. As the new models shipped and the cycle turned, the stock rose more than tenfold over the following five years.
The crowd's verdict is not analysis. The balance sheet and the showroom said something different from the headlines.
There is no fixed count. Weigh severity and how they cluster: several reinforcing signals around the same weakness matter far more than a few unrelated minor flags. The goal is to size the risk, then demand a margin of safety that compensates for it.
No. Technical sell signals come from price and chart patterns. Risk signals here are fundamental and qualitative — they question the durability of the business and the honesty of the numbers, not the shape of the chart.
Make risk-signal checks part of every thesis:
Download Valuefocus